Key Takeaways
- Compare the annual percentage rate, fees, repayment length, and total amount due.
- A smaller monthly payment can still lead to a higher overall borrowing cost.
- Review the payment schedule and withdrawal authorization before accepting a loan.
- Ask about late fees, returned-payment charges, and early payoff terms.
- Use a realistic monthly budget to decide whether a payment is manageable.
- Keep a copy of the final agreement and records of all lender communications.
From Salt Lake City to smaller communities along the Wasatch Front and throughout rural Utah, an unexpected car repair, medical bill, or utility expense can make fast access to funds feel important. Before applying for installment loans online in Utah, take the time to compare the full terms of each offer rather than focusing only on the payment amount. An installment loan can provide a set borrowing amount and a scheduled repayment plan, but the details determine whether the loan fits the borrower’s budget. Reviewing the annual percentage rate, fees, payment dates, and total repayment amount can help Utah consumers make a more informed decision before signing an agreement.
Why Comparison Matters
Two offers for the same loan amount can produce very different costs. One lender may offer a lower payment over a longer term, while another may require a higher payment but allow the balance to be repaid sooner. Neither option is automatically better. The right comparison looks at the total amount to be paid and whether each scheduled payment fits comfortably within the household budget. For example, extending a repayment period can reduce each payment, but interest may continue to accrue for more months. Review the disclosure carefully and write down the loan amount, number of payments, payment amount, due dates, and total repayment for every offer being considered.
How Installment Loans Work
An installment loan is repaid through scheduled payments over a defined period. Payments are commonly due weekly, biweekly, semimonthly, or monthly. The agreement should explain how much is due, when it is due, and what happens if a payment is missed or returned.
- Principal: The amount borrowed before interest and applicable charges.
- Interest: The cost charged for borrowing money.
- APR: The annual percentage rate, which can help compare the cost of similar loan offers.
- Term: The scheduled length of time for repayment.
- Payment schedule: The timing and frequency of required payments.
- Total repayment: The full scheduled amount due if the loan is paid according to the agreement.
Costs to Review Before Signing
Read the agreement line by line before providing bank information or accepting funds. In Utah, consumer lending and certain related activities are governed by the Utah Consumer Credit Code, and the Utah Department of Financial Institutions provides information on consumer lending for people seeking to understand the state’s oversight framework.
Compare These Details
- The amount actually received after any permitted charges are deducted.
- The interest rate and APR.
- The exact number and amount of payments.
- The total amount scheduled for repayment.
- Late-payment, returned-payment, or insufficient-funds fees.
- Whether optional products or services add to the cost.
- Whether early payoff is permitted and how the payoff amount is calculated.
- How electronic payments are authorized and processed.
Do not assume a loan with the smallest payment is the least expensive. Compare the total repayment amount alongside the payment amount, especially when offers have different terms.
Testing the Payment Against Your Budget
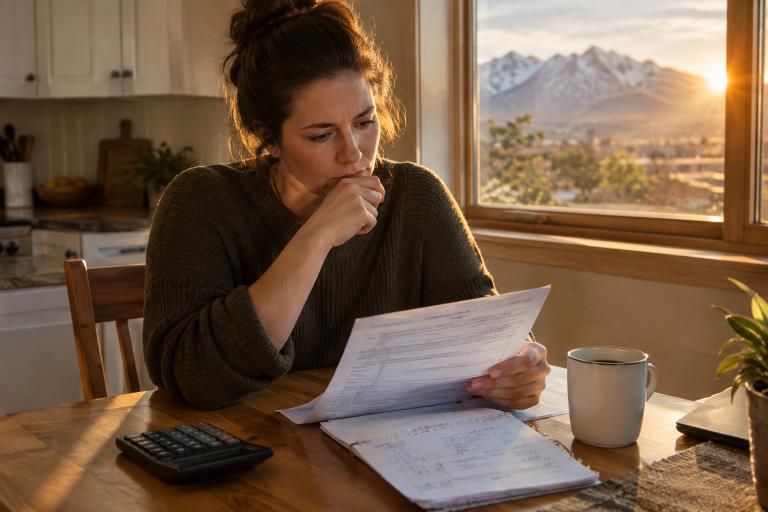
A payment that looks manageable on an application screen may be difficult when rent, groceries, transportation, insurance, and existing debt are due. A quick budget check can show whether the loan would leave enough room for regular expenses and unexpected costs.
A Simple Three-Step Budget Test
- List dependable monthly take-home income.
- Subtract essential expenses, existing debt payments, and planned savings contributions.
- Subtract the proposed loan payment and leave a cushion for variable costs.
Also consider the payment date. A due date that falls before payday can create avoidable pressure, even if the same payment would be manageable a few days later.
Questions to Ask a Lender
- What is the total amount I will repay if I make every payment as scheduled?
- Are there fees at origination, for late payments, or for failed withdrawals?
- When is the first payment due, and how often are later payments due?
- Can I pay the loan off early?
- Will payments be withdrawn automatically from my bank account?
- What options are available if I expect difficulty making a payment?
- Who can I contact for account questions or a copy of my agreement?
Warning Signs to Watch For
Consumers should be cautious when an offer is difficult to understand or creates pressure to act immediately. Take extra time when a lender will not clearly state the total repayment amount, asks for money before approval, leaves blanks in the contract, or changes terms after an initial offer. Never share passwords, send gift cards, or use unusual payment methods to secure a loan.
If a Payment May Be Late
Contact the lender through its official customer service channel as soon as a problem becomes likely. Ask whether a payment-date change or short-term arrangement is available, and keep written notes of the conversation. Review the agreement before accepting any new arrangement. For certain covered payday and installment lenders, federal rules limit additional withdrawal attempts after two failed attempts unless the borrower provides new authorization. Rules on repeated account withdrawal attempts can help borrowers understand why monitoring bank activity matters.
Alternatives to Consider
- Ask a utility, landlord, medical provider, or other biller about a payment arrangement.
- Check whether an employer offers an earned-wage or emergency assistance program.
- Compare small-dollar lending options available through local credit unions.
- Look into community support for food, housing, health care, or utility expenses.
- Consider temporary income or selling unused items when practical.
- Speak with a nonprofit credit counselor about a plan for existing debt.
Common Questions
Is the lowest monthly payment always the best option?
No. A lower payment may result from a longer term, which can increase the total amount repaid. Compare both figures before choosing.
Is APR more useful than the interest rate?
Both are important. APR can provide a broader way to compare similar loan offers, but borrowers should still read every fee and repayment term in the agreement.
Can an installment loan be paid off early?
That depends on the agreement. Ask about early payoff before accepting the loan and request the answer in writing when possible.
Conclusion
Comparing installment loan offers in Utah starts with looking beyond the advertised payment. Review the APR, total repayment, fees, payment timing, loan term, and late-payment rules to understand the full cost and obligations involved. Borrowers should also check whether the payment schedule fits their regular income and existing monthly expenses. Comparing offers from different lenders can make differences in interest rates, fees, repayment periods, and other terms easier to identify. It is also important to read the loan agreement carefully and confirm what happens if a payment is late or if the borrower wants to pay the balance early. A few careful minutes before signing can help prevent costly surprises and support a borrowing decision that better fits real life, current financial needs, and the borrower’s ability to repay the balance on time.