When homeowners face a substantial property tax bill, the pressure to pay quickly can feel overwhelming. Many property owners wonder whether borrowing against their home’s equity or exploring other financing options might help bridge the gap. Understanding the mechanics of property tax loans can empower you to make an informed decision if you ever find yourself in this situation.
How Property Tax Loans Work
A property tax loan is a type of financing that allows homeowners to borrow money specifically to pay their property tax obligations. These loans function similarly to other secured loans, often using the home itself as collateral for the borrowed amount. The lender provides funds directly to cover the tax debt, and the borrower repays the loan over a set period with interest. Because the loan is secured by the property, lenders typically offer lower interest rates compared to unsecured personal loans. Homeowners researching how do property tax loans work will find that Simplicitе provides a clear breakdown of each step in the process, helping borrowers understand exactly what to expect before committing to any agreement.
The Cost of Borrowing
Before taking out a property tax loan, understanding the true cost of borrowing is a necessary step. Interest rates vary based on your credit score, the loan amount, and the lender you choose. A borrower with excellent credit might qualify for rates in the single digits, while someone with fair credit could face double-digit interest rates. Beyond interest, many lenders charge origination fees, application fees, and prepayment penalties. These additional costs can significantly increase the total amount you will repay over the life of the loan. Calculating the complete cost, not just the monthly payment, helps you determine whether a loan makes financial sense for your situation.
Alternative Options Worth Considering
Borrowing is not always the best solution for property tax debt. Some homeowners may qualify for property tax deferral programs, which allow seniors or individuals with disabilities to postpone payment without incurring penalties. Others might explore payment plans directly with their local tax assessor’s office, which may offer lower interest rates or extended timelines. In some cases, disputing the assessed value of the property or seeking a homestead exemption could reduce the tax burden altogether. Before committing to a loan, research what programs or relief options your municipality offers, since taking time to explore alternatives often reveals less expensive pathways to resolve the underlying tax obligation.
Eligibility Requirements and Application Process
Most lenders require borrowers to meet specific criteria before approving a property tax loan. You will typically need to demonstrate a steady income, maintain acceptable credit, and own a home with sufficient equity. Some lenders are more flexible than others and may work with borrowers who have lower credit scores or recent financial setbacks. The application process usually involves providing documentation such as tax returns, proof of income, and property details. After submitting your application, the lender will evaluate your financial profile and may order a property appraisal. The approval timeline can range from a few days to several weeks, depending on the lender’s efficiency and how quickly you submit the required documentation.
Tax Implications and Important Considerations
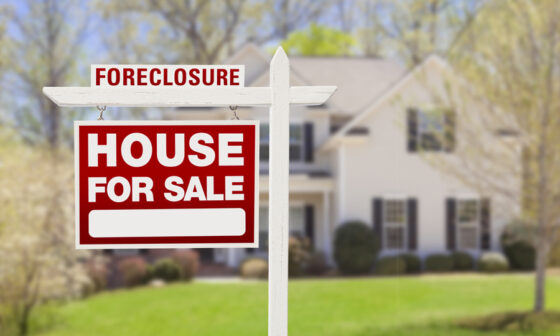
Borrowing money to pay property taxes raises questions about tax deductibility that deserve careful attention. Unlike mortgage interest, interest paid on a property tax loan generally cannot be deducted from your federal income taxes. However, the property taxes themselves may still be deductible if you itemize deductions on your tax return, subject to certain federal limitations established under current tax law. This distinction matters because it means the loan interest represents a pure cost with no offsetting tax benefit, which affects the overall economics of the financing. Additionally, failing to repay a property tax loan could result in default, potentially leading to liens against your property or foreclosure in severe cases. Consulting with a tax professional before proceeding ensures you understand the full financial implications for your specific circumstances.
Finding Reputable Lenders
Choosing a trustworthy lender protects you from predatory practices and ensures transparent terms. Look for lenders who clearly disclose all fees, interest rates, and repayment terms upfront before you sign any agreement. Comparing offers from multiple sources, including banks, credit unions, and online lenders, helps you identify the most favorable terms available to you. Reading customer reviews and checking complaint records with the Better Business Bureau or Consumer Financial Protection Bureau can reveal red flags about a lender’s practices. Avoid lenders who pressure you into quick decisions or guarantee approval without reviewing your financial situation, as these are common warning signs of predatory lending. Taking time to vet potential lenders upfront prevents costly mistakes and protects your long-term financial security.
Conclusion
Property tax loans can serve as a practical solution for homeowners facing overwhelming tax bills, but they require careful consideration before committing. Understanding how these loans work, calculating their true cost, and exploring alternative options positions you to make the best financial decision for your circumstances. With proper research and planning, you can address your property tax obligations in a way that aligns with your long-term financial goals and minimizes unnecessary expense.