When a storm passes, the first priority is protecting people and preventing additional damage. The next priority is understanding whether home insurance covers roof repairs in your particular situation. A roof claim is rarely decided by one photograph or one contractor estimate. The policy language, the cause of damage, and the records you keep all matter.
This guide offers a practical starting point for homeowners dealing with missing shingles, leaks, fallen branches, or suspected hail damage. It is not a substitute for your policy or professional advice, but it can help you make safer, better-organized decisions when time matters.
1. What To Do In The First Few Hours
The rain may have stopped, but hazards can remain. Keep family members and pets away from areas beneath sagging ceilings, loose roofing, fallen limbs, or damaged electrical fixtures. If water is near outlets, light fixtures, or the electrical panel, avoid touching it and contact an electrician or emergency service when appropriate.
Move furniture and valuables away from active drips if it is safe to do so. Use buckets, towels, or plastic sheeting indoors, then call a qualified roofer for roof access and temporary protection. Post-storm guidance often stresses quick documentation and scam awareness because rushed decisions can create expensive problems.
2. Signs Of Roof Damage
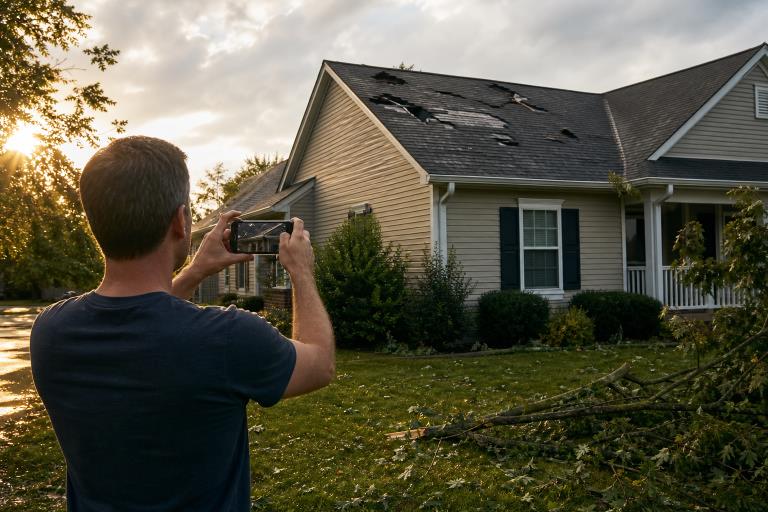
Some roof damage is obvious, but much of it is not visible from a driveway. Look for missing, lifted, curled, or cracked shingles; debris in the yard; dents on gutters, vents, flashing, or siding; and granules collecting near downspouts. Inside, check ceilings, upper walls, attic insulation, and framing for stains, dampness, musty odors, or fresh drips.
A homeowner may see no obvious hole from the ground, yet damaged flashing around a vent or chimney can let water into the attic during the next heavy rain. Take clear photos from safe locations and arrange a professional inspection if damage is suspected.
3. Why The Cause Of Damage Matters
Insurance claims commonly distinguish sudden, accidental events from gradual deterioration. Wind, hail, lightning, fire, falling trees, and certain snow or ice events may be covered when the policy includes those risks. Wear, rot, mold, pests, installation defects, clogged gutters, and known leaks that were left unrepaired may be treated differently.
Do not guess about the cause. Write down the date and time of the storm, save weather alerts if available, and record when you first noticed the problem. A clear timeline can help explain whether a leak followed a specific event or developed over time.
4. Roof Leaks And Interior Water Damage
A roof problem can quickly become an interior damage problem. Water entering through a storm-created opening may affect insulation, ceilings, walls, flooring, furniture, and personal belongings. Coverage can depend on the water source, the cause of the opening, and whether the damage was sudden or gradual.
- Place containers below drips when conditions are safe.
- Photograph affected rooms before moving belongings.
- Dry wet materials quickly to reduce further damage.
- Keep damaged materials until the insurer says otherwise.
- Save receipts for emergency mitigation, cleanup, and temporary lodging.
5. Policy Details That Can Change The Outcome
Replacement Cost And Actual Cash Value
Replacement-cost coverage is generally intended to reflect the cost of comparable new materials, subject to the policy terms. Actual-cash-value coverage may subtract depreciation. For example, two homeowners with similar wind damage could receive different settlements if one has a newer roof with replacement-cost coverage and the other has a ten-year-old roof valued at actual cash value.
Deductibles, Age, And Condition
Your deductible is the amount you may pay before covered insurance funds apply. Some policies use separate deductibles for wind, hail, or named storms. Roof age, material type, previous repairs, and maintenance history may also affect the outcome. Recent reporting on hail-claim disputes is a useful reminder to review estimates and settlement terms carefully rather than relying on assumptions.
6. A Simple Roof Claim Process
- Review your policy:Check covered causes, exclusions, deadlines, deductibles, and roof valuation language.
- Document the loss:Take wide and close photos, note the storm date, and retain inspection reports.
- Prevent more damage:Arrange reasonable temporary protection without taking unsafe risks.
- Report the claim:Ask which documents, deadlines, and inspection steps apply.
- Compare estimates:Review labor, materials, flashing, ventilation, permits, and debris removal.
- Ask in writing:Request explanations for depreciation, omitted items, or denied portions.
7. How To Choose A Roofing Contractor
Severe weather can attract legitimate contractors and opportunistic ones. Verify licensing and insurance requirements in your state, confirm a physical business address, request local references, and get a written estimate that separates labor and materials. Read every contract before signing, avoid large cash deposits, and be cautious when someone promises guaranteed claim approval or a “free” roof.
Working with a licensed Roofing contractor helps ensure that temporary tarping and permanent structural repairs are documented accurately for the insurance adjuster. Professional assessment also reduces the risk of overlooked flashing damage or hidden structural issues that could lead to denied claims later in the process.
Working with regional professionals who understand local building codes and weather patterns helps ensure that post-storm repairs meet safety standards and policy requirements. Property owners in Massachusetts often consult Wakefield roofing contractors from Peak Quality Roofing to evaluate structural issues, assist with detailed damage documentation, and complete necessary structural fixes before minor leaks worsen.
8. Common Mistakes To Avoid
Common errors include climbing on a roof without proper equipment, discarding damaged materials too early, waiting too long to report a known loss, and completing permanent repairs before documentation. Do not sign over claim payments without understanding the agreement, assume every leak came from the latest storm, or rely only on a contractor’s opinion about insurance coverage.
9. Roof Care Before The Next Storm
Routine maintenance cannot prevent every disaster, but it can reveal weaknesses early. Clear gutters and downspouts, trim overhanging limbs, address small flashing or sealant failures, and have attic ventilation and insulation checked periodically. Keep inspection reports, repair receipts, and photographs of the roof in good condition in one digital folder.
Proper attic ventilation and insulation are essential components of seasonal home maintenance, as poor airflow and insulation issues can exacerbate roof degradation during extreme weather. Homeowners looking to safeguard their home can consult specialists like Sensigreen Heating, Cooling & Insulation to evaluate attic insulation levels, which helps maintain consistent indoor temperatures and limits energy loss throughout the year.
For a simple 2026 planning routine, review your policy annually, confirm your deductible, check whether the roof is valued at replacement cost or actual cash value, and save your insurer’s claim contact information before storm season begins.
10. Final Thoughts
Roof claims are easier to manage when homeowners act safely, document carefully, understand the policy, and separate sudden storm damage from ordinary aging. Ask questions before water enters the home, keep complete records, and use qualified professionals when roof access or repairs are needed. A calm plan can make the next step much clearer.