Key Takeaways
- The best Long Island home is one that supports everyday routines, travel needs, and plans, not simply the one with the most space.
- Waterfront, village, suburban, and North Fork properties can deliver very different experiences at similar price points.
- Taxes, insurance, maintenance, utilities, and property condition should be compared alongside the purchase price.
- Recent closed sales, local inventory, and a home’s specific condition matter more than an asking price alone.
- A structured scoring process can make an emotional decision more practical.
Long Island, New York, is not a single-lifestyle market. A cottage near a harbor, a classic home near a walkable downtown, a larger inland property with a pool, and a North Fork retreat may all appeal to the same buyer for entirely different reasons. Buyers who want help interpreting those differences can benefit from a local perspective. Long Island luxury realtors at The Agency Northeast work across communities, including the North Shore, South Shore, Gold Coast, Fire Island, and North Fork-Southold. The Agency Northeast is a regional real estate brokerage whose local office network and property-focused services can be useful when comparing location, home type, and long-term fit rather than viewing each listing in isolation.
Start with the Lifestyle Test
Before saving listings, define what an ordinary week should look like after the move. A beautiful home can become inconvenient if it creates a commute, maintenance load, or travel pattern that does not suit the household.
- Name the priorities. Write down the activities that matter most, such as boating, gardening, dining out, hosting family, working from home, or reaching a train station.
- Choose between access and privacy. A walkable village setting may reduce driving, while a more secluded property may offer a larger outdoor space and greater separation from nearby homes.
- Test regular travel. Consider how often household members travel to New York City, Brooklyn, Queens, airports, schools, or other parts of Long Island.
- Think beyond today. Ask whether the home should work as a year-round residence, second home, multigenerational space, or potential future rental, subject to local rules.
Waterfront Homes Versus Inland Properties
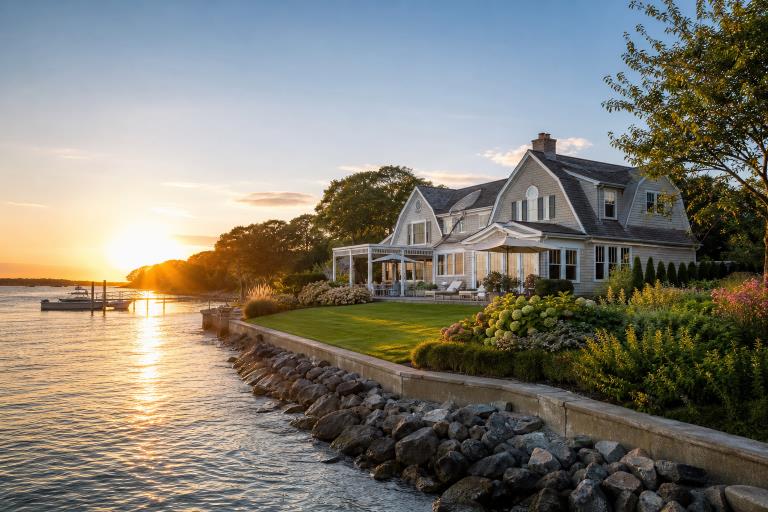
Waterfront and water-view homes can offer scenery, outdoor living, privacy, and, in some cases, direct boating access. Those benefits deserve a more detailed review than a standard interior tour. A view of the water does not automatically mean a private beach, a dock, navigable water access, or permission to add shoreline improvements. Review flood exposure, drainage, bulkheads, seawalls, docks, erosion concerns, prior repairs, and permit history early in the process. The FEMA Flood Map Service Center allows buyers to look up official flood-hazard information by address. Still, it should be used alongside insurance quotes, seller disclosures, inspections, and advice from qualified local professionals. Where possible, revisit a coastal property in different conditions. Wind, high water, road drainage, and noise can feel very different on a calm afternoon than they do during a wet or stormy period. Budget for the systems that make waterfront ownership possible, not only the house itself.
Village Convenience or Suburban Space?
Village Properties
Village living may suit buyers who want restaurants, shops, parks, libraries, and community events closer to home. These properties can also offer a stronger sense of daily connection because errands and social plans may require less driving. The trade-off may include smaller lots, closer neighbors, tighter parking, older building systems, and local rules that affect exterior changes or additions.
Suburban Properties
Inland suburban homes may offer larger yards, garages, home offices, pools, and room to expand. They can be especially attractive to buyers who value storage, entertaining space, or privacy. However, more land generally means more upkeep. Review landscaping, tree care, snow removal, irrigation, pool equipment, drainage, and the practical need for one or more vehicles.
Include the North Fork and East End in the Comparison
The North Fork and other East End locations appeal to buyers seeking beaches, farmland, vineyards, open views, and smaller communities. A second-home buyer may see it differently from someone who needs year-round access to medical care, groceries, schools, reliable internet, and everyday services. Test the trip at the times you would actually travel. A route that feels simple on a quiet weekday can be more demanding during summer weekends or holiday periods. For homes with wells or septic systems, ask for relevant records and arrange appropriate inspections. Buyers should also understand nearby agricultural activity, zoning, and maintenance needs before assuming a rural setting will remain unchanged.
Build a Full Cost Comparison
A lower purchase price does not always create a lower cost of ownership. Create the same estimate for every serious contender, using conservative numbers where information is incomplete.
- Monthly housing cost: mortgage principal and interest, property taxes, homeowners’ insurance, flood insurance if applicable, and association fees.
- Utilities: heating, cooling, electric, water, sewer or septic service, internet, and fuel, where applicable.
- Property upkeep: roof, siding, windows, landscaping, drainage, driveway, pool, dock, bulkhead, or shoreline work.
- Purchase and move-in expenses: inspections, attorney and title services, lender fees, moving, furnishings, and immediate repairs.
- First two years: reserve funds for upgrades, deferred maintenance, and surprises found after closing.
For each of the three homes, total the estimated monthly cost, annual cost, and expected one-time expenses. Then compare the result against available savings and the remaining flexibility in the household budget.
Review the Market Before Making an Offer
Asking prices are useful starting points, not proof of value. Review recent closed sales that resemble the home in location, lot characteristics, condition, size, and improvements. Also consider how long the property has been available, whether its price has changed, and whether competing buyers are likely. A home may command a premium because of its condition or setting, but buyers should still ask what supports that premium. A well-prepared offer balances price with financing strength, timing, inspection rights, and the buyer’s comfort with the property’s risks.
Property Research Checklist
Before the Tour
- Review taxes, listing history, disclosed improvements, permits, and likely insurance costs.
- Drive or ride key commute routes during normal travel hours.
- Check nearby development, transportation, services, and potential noise sources.
- Prepare questions about drainage, utilities, heating, renovations, and included fixtures.
During and After the Tour
- Look for moisture, roof wear, window condition, electrical concerns, drainage issues, and visible foundation problems.
- Listen for traffic, trains, aircraft, commercial activity, and neighboring outdoor noise.
- Score each property for lifestyle, location, condition, cost, and future flexibility.
- Use the homebuyer FAQ from the Long Island Board of REALTORS® to frame questions about inspections, financing, title matters, and buyer representation.
Final Decision Framework
Before moving forward, rate each finalist from 1 to 5 in five categories: lifestyle fit, location in every season, condition and repair needs, total ownership cost, and flexibility if work, family, or travel plans change. Give each category a score based on what you actually need, not what looks impressive in a listing. Consider commute times, nearby services, property taxes, insurance, utilities, maintenance, renovation needs, and potential future expenses when comparing the overall cost. It can also help to revisit the neighborhood at different times of day and during different seasons to understand traffic, noise, weather conditions, and everyday convenience. The strongest choice is not necessarily the newest, largest, or most dramatic property. It is the Long Island home that fits the way you intend to live, matches your financial comfort level, and leaves enough room to handle the realities and unexpected responsibilities of homeownership.